
Investigation | By Lotta Goddess | November 10, 2026
It begins with an envelope. Sometimes the letter arrives only weeks after a funeral. It asks for money the family did not realize Medicaid might reclaim, and it comes with a clock.
When Frances Ruhl died in Perry, Iowa, in January 2022, the state sent her family a notice seeking $226,611.35 for Medicaid spending. Her surviving husband, Henry, lived in their modest 832-square-foot home, assessed at $81,470 for property taxes. Their daughter, Jen Coghlan, faced the prospect that the home might someday have to be sold after her father died. The letter gave the family 30 days to respond, KFF Health News reported in March 2023.
The Ruhl case is not a story about Medicaid instantly seizing a house: the surviving spouse’s protections matter, the entire $226,611 was not magically collectible from an $81,470 property, and the future recovery depended on remaining assets and the law. But it reveals what our new investigation found by comparing government guidance across the country: the family not only inherits the paperwork; it inherits a different legal calendar depending on the state.
To help readers find the relevant rule before a deadline passes, Apep Bar has published a 50-state Medicaid estate-recovery and hardship lookup, with statutory starting points, agency links, contact numbers and a searchable A-Z navigator. This exposé examines what those rules expose about the system, the decisions legislators made, and the lines between lawful collection and uneven protection.
One federal mandate, fifty different definitions of mercy
The federal government did not order states to send heirs identical forms or use identical deadlines. Congress, through 42 U.S.C. §1396p, requires states to pursue certain Medicaid long-term-care costs from estates of people who received services at age 55 or older, subject to survivor protections. The federal law also requires a process for waiving recovery when it would cause an undue hardship. Yet it does not prescribe one nationwide dollar threshold, mandatory caregiver definition, application form or filing timetable.
As a result, the same kind of family farm might meet one state’s livelihood test but fail another state’s means test. One adult child may be offered a waiver, which can cancel a claim. Another can win only a deferral, with recovery potentially resuming when the circumstances change. And a claimant in a third state may have a smaller amount to dispute because the state chose to limit which services are recoverable.
Those are policy choices inside a federal framework—not proof of a covert national plot to confiscate homes. And they are consequential: the KFF 2024 state survey found that 32 responding states pursued all Medicaid benefits for at least some recipients 55 or older, another five recovered some optional benefits, and 30 recovered managed-care premiums. Florida did not respond to that survey, and service rules have changed in some states since. Historical counts must not be passed off as a verified 2026 census.
The first trap is time: different filings, different clocks
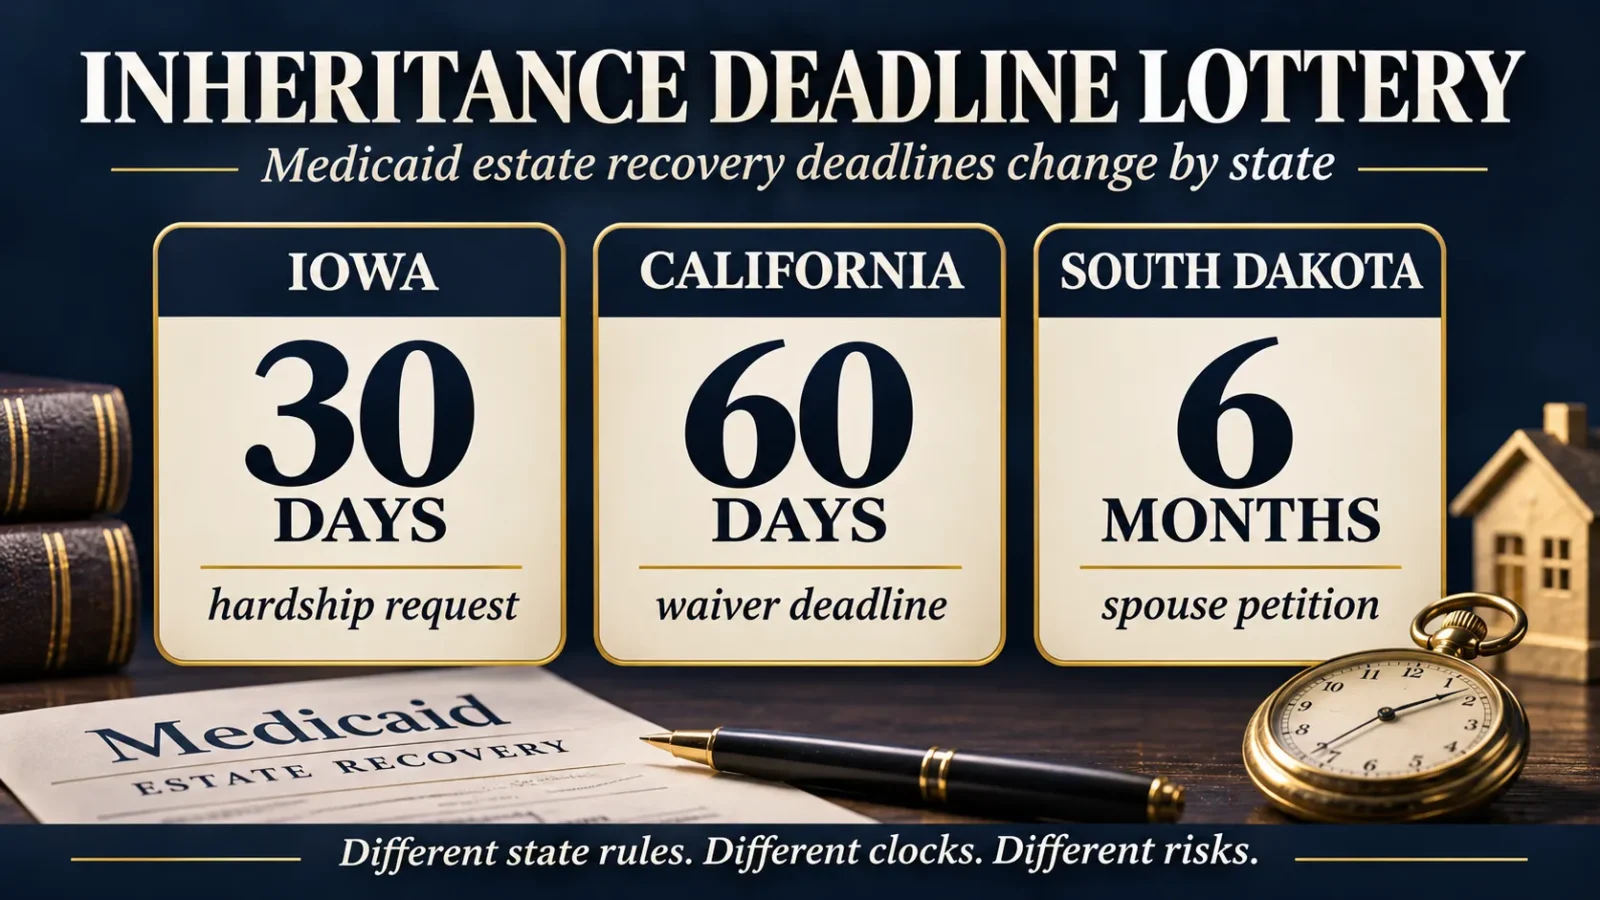
| State | Verified time limit | What the deadline concerns |
|---|---|---|
| Iowa | 30 days after the family receives the notice | Request for estate-recovery hardship relief under Iowa HHS guidance |
| California | 60 days from the DHCS claim letter | Application for substantial-hardship waiver |
| Georgia | 30 days after receipt of the estate claim | Hardship request described in the state’s September 2025 FAQ |
| South Dakota | Six months after the recipient’s death | Special petition by a surviving spouse to limit later recovery from the spouse’s estate |
These are not four versions of the same deadline. South Dakota’s six-month period concerns a surviving spouse’s particular petition; it does not grant every heir six months to dispute a normal claim. In California, the state may have sent the claim letter long after the date of death; its 60-day waiver clock is measured from the claim letter instead. Iowa measures its hardship period from the family’s receipt of the notice. Georgia’s 2025 guidance refers to receipt of its Medicaid estate claim.
Primary records: Iowa HHS estate recovery; California DHCS; Georgia’s official 2025 FAQ; and South Dakota’s estate recovery office.
Why does this matter? Grieving families must locate paperwork, identify legal beneficiaries, contact agencies and sometimes afford counsel almost immediately. An heir who misses one form can lose a chance to assert an otherwise applicable exception. That is a procedural risk, not a finding that the state automatically wins a foreclosure because a calendar page turned.
Iowa makes the hurdle explicit: income, savings and necessity
Iowa’s official estate-recovery page identifies a hardship request process with conditions that are considerably more specific than the word “hardship” sounds. The heir’s household income must be below 200% of the federal poverty level, resources must be no more than $10,000, and collection must deprive the family of necessities such as food, shelter, clothing or medical care in a way that endangers life or health. The state says a reduced inheritance alone is insufficient.
That is a demanding test. A family can have very little liquid savings yet own a home that does not neatly satisfy the agency’s prescribed conditions. The claim may also include the state’s managed-care capitation payments—monthly payments to insurers even in months when the plan paid no direct services for the member, as Iowa itself explains. The amount on a demand letter is therefore not necessarily an itemized list of procedures received by the decedent.
There is another distinction worth guarding: a six-figure Medicaid claim is generally a claim against assets in the estate, not personal debt created merely because someone is a daughter or son. The Ruhl family’s story does not prove the state can collect its full demand, only that it can assert one.
California chose a narrower target; the deadlines survived
California’s SB 833 changed Medi-Cal estate recovery for people dying on or after January 1, 2017: the state generally limited recovery to the probate estate and the federally required categories of long-term care and related services. That can substantially reduce what families face compared with the pre-2017 model. But it does not make every will or every home safe.
The state’s recovery page says the representative should give notice of death within 90 days, and it separately describes a 60-day period from the estate-recovery claim letter to submit a substantial-hardship waiver application. Confusing these two different notice duties could create serious problems. The lesson is not that California abolished estate recovery; it is that legislators narrowed its reach while keeping a formal claims process.
Texas: 2026 guidance changed a number many websites still repeat
One of the sharpest findings is a change in the information Texas gives heirs. Older summaries of its Medicaid Estate Recovery Program cite an estate threshold of $10,000 and a recoverable-cost threshold of $3,000. But the Texas Health and Human Services public guide available in November 2026 states the program will not seek repayment when the estate is worth $15,000 or less or Medicaid costs are $5,000 or less, among other circumstances.
Those two dollar figures are separate exceptions, not a blanket $15,000 exemption from every family’s house. Texas’ hardship rules also consider whether the home is below a defined homestead value and whether heirs satisfy household-income requirements. A relative who follows an older article without checking the agency’s current page could misread the options. That is precisely why we built an updateable 50-state directory linking to source agencies rather than declaring one forever-valid national chart.
Texas added another 2026 twist: its state website states that MERP operations transitioned to Stellarware Corporation on September 1, 2026. This confirms that contractor administration is a real part of the process; it does not establish misconduct, improper incentives or illegal collections. Still, when families receive mail from a name other than their state agency, official verification becomes even more important. The state supplies a program FAQ and hardship application details.
Tennessee offers a startling example: paying an insurer is itself a recoverable cost
TennCare’s official guidance, updated with June 1, 2026 monthly amounts, goes further than the usual broad warning about nursing homes. In Middle Tennessee, for example, a CHOICES Group 1 or 2 member who has Medicaid but not Medicare had a stated long-term-care monthly capitation amount of $6,834.40 as of that update. Rates vary across groups, Medicare status and regions.
And Tennessee explains that the recoverable long-term-care share can be due even when the insurer did not furnish the expected direct care during a given month. Its own example includes a CHOICES member hospitalized for six months while the state continued paying the managed-care plan. This is a legal reimbursement rule tied to the public payer’s contract; it should not be mislabeled as proof that an individual nursing home secretly overcharged the patient.
Tennessee also distinguishes a permanent waiver for an income-producing family farm or business that qualifies under its policy from a temporary delay for a qualifying resident caregiving adult child or sibling. Moving out or selling the home may change that protection. A family needs to read the exact decision letter, not simply celebrate that it “won hardship.”
Washington’s relief can be only a pause
Washington’s WAC 182-527-2750 describes hardship as a ground to delay recovery when a property is an heir’s sole income-producing asset, when collection would deprive an heir of shelter and the heir cannot afford an alternative, or when a surviving state-registered domestic partner is involved. When hardship ends, the debt may again become collectible.
A pause can be invaluable: it may keep a surviving relative housed while a crisis is ongoing. But it is not identical to a waiver. Compare that with Massachusetts, which generally waives recovery against probate estates valued $25,000 or less, while also narrowing recoverable care categories for many deaths beginning August 2024. Or with Pennsylvania, whose estate program has particular hardship provisions for certain low-value estates, caregiving residents and income-producing family property. These thresholds cover different things; lining up dollar amounts without defining their legal triggers would mislead readers.
Vermont asks a more personal question: who depended on the home?
Vermont’s Department of Vermont Health Access describes caregiver-based homestead protections and a special rule involving the first $250,000 of a homestead where qualifying relatives inherit and conditions concerning household income or meaningful care are met. Its guidance includes an income standard below 300% of the federal poverty level in one pathway and evidence that family care delayed institutional care by at least six months in another.
That is not a blanket $250,000 exclusion for every Medicaid recipient. The residence, beneficiary’s relationship, care history, income and paperwork all matter. But it is a revealing counterexample to the idea that every state must treat the family house as merely the largest available account balance.
The statistical inequity legislators cannot pretend not to see
KFF documented that states recovered roughly $733 million nationwide in fiscal year 2019—approximately 0.1% of that year’s Medicaid spending. Five states—Massachusetts, New York, Pennsylvania, Ohio and Wisconsin—accounted for nearly 40% of collections that year. That is a historical picture, not a 2026 estimate.
The same research found that hardship requests in a 10-state MACPAC sample were approved at rates ranging from 29% in New York to 95% in Iowa in 2019. These were applications submitted under different state criteria, not a controlled experiment proving one state’s caseworkers are fairer. They nevertheless make an important point: the rules, who applies, and whether a request succeeds differ dramatically. Source: KFF’s 2024 issue brief and MACPAC’s recommendations.
Defenders of estate recovery argue that expensive long-term care was financed by taxpayers, and estates with assets should help reimburse the program. Critics answer that a complicated claims apparatus collects little compared with total spending while posing a serious intergenerational wealth risk to families with no investment portfolio, only a modest home. Both propositions belong in the analysis. The numbers do not settle the moral question for us.
A federal bill would end the requirement—but has not done so
Introduced January 6, 2026, the Stop Unfair Medicaid Recoveries Act, H.R. 6951, proposes repealing the federal estate-recovery requirement and restricting certain property liens. As of the available November 2026 congressional records, it had been referred to the House Energy and Commerce Committee; it is a proposal, not law. Meanwhile the federal Medicaid estate-recovery requirement remains in place.
MACPAC has separately recommended making estate recovery optional, addressing managed-care capitation treatment, and establishing stronger minimum federal hardship-waiver standards. Those reforms would preserve some choices for states while removing the most unpredictable traps. Legislators could also require plain-language notice and a national baseline response period, although those are editorial proposals, not enacted rights.
What the claim letter should never obscure
A family may demand an itemized legal explanation rather than assuming a frightening number is automatically collectible. An heir may be protected by federal survivor rules. A hardship waiver may be available, but missing the deadline can complicate the process. Title records can reveal whether a lien was actually recorded. State law, date of death and care category can change the outcome. And an ordinary adult child is not generally personally liable for a Medicaid estate claim merely because they are related to the person who died; separate private care bills, filial-support statutes or signed guarantees raise different legal questions.
Our 50-state lookup points to the relevant statute, official estate-recovery page and agency number for each state. If a notice has arrived, preserve the envelope, ask immediately about hardship and appeal rights, and seek local elder-law or legal-aid advice before moving or selling an asset. Use the CMS state Medicaid directory as a fallback if an agency changes its contact page.
This story builds on our earlier investigation into the Medicaid house trap and the reach of all 50 states’ laws. Its deeper finding is procedural: Congress gave every state a recovery duty. It did not guarantee every family an equally understandable path to ask for mercy. How much home equity should depend on a deadline written by a state legislature—and how many Americans can realistically navigate that deadline after a death?
Primary evidence and further reading
- Centers for Medicare & Medicaid Services: estate-recovery rules; 42 U.S.C. §1396p.
- KFF Health News, 2023: the Frances Ruhl family and the actual Iowa demand; KFF, 2024: state survey, hardship differences, collections.
- Iowa HHS; California DHCS; Georgia DCH 2025 FAQ; South Dakota DSS.
- Texas HHS: current MERP guidance; Texas Register: August 2026 administrative rule amendments; TennCare: 2026 capitation figures and waivers.
- Washington WAC: hardship delay; Vermont: homestead and caregiver waivers; Massachusetts: reformed program.
- MACPAC: recommendations for reform; H.R. 6951, proposal and legislative status.
Contextual video: why this story spread
Watch the original homeowner-warning commentary video. Contextual commentary only. The viral account of a $190,000 home, $114,000 claim and 60-day foreclosure threat has not been substantiated as a specific court case; this article relies on official records and independently documented families instead.
Editorial/legal note: This is a November 10, 2026 investigative comparison, not legal advice. The dates, statutes, family eligibility and recovery categories for an actual case require independent state-specific verification. The article distinguishes agency rules and published investigations from proposed reforms and the author’s analysis.