
Investigation | By Lotta Goddess | November 10, 2026
A house can be fully paid off—and still carry a bill the family never knew existed. A viral video describes an heir who supposedly inherited a $190,000 home, then received a $114,000 Medicaid lien with 60 days to pay or face foreclosure. The specific story has not been independently substantiated. Yet the law behind the fear is real, and its reach changes dramatically when you cross a state line.
In California, the state generally looks to the deceased person’s probate estate and the long-term-care spending federal law requires. In Iowa, recovery can reach more forms of property, and a claim can reflect payments to private managed-care insurers rather than a simple list of nursing-home bills. In Massachusetts, lawmakers narrowed recovery in 2024. In Tennessee, officials pursued a claim exceeding $225,000 while a daughter fought to keep the house. This is the Medicaid estate-recovery system: one federal mandate, 50 versions of the afterlife of a medical bill.
What we verified: federal and state law, the Centers for Medicare & Medicaid Services (CMS) guidance, a national KFF state survey, statutory provisions, and independently reported cases. What remains unverified: the identity, location, notice, lien recording, and threatened auction in the viral $114,000 story.
First, the viral house story: real law, unverified facts
The supplied video commentary describes a worker’s mother who left a paid-off home worth approximately $190,000. Four months of rehabilitation allegedly produced a $114,000 claim and a 60-day ultimatum. The video offers useful warnings but does not establish that this specific estate was foreclosed upon, that the demand was legally valid, or even which state’s laws applied. A demand letter, a filed probate claim, a lien recorded against title, and a court-ordered foreclosure are four different legal events.
A four-month stay alone does not explain the figure without the actual billing history. The recovery amount may include different periods of services, related medical care, and—where allowed—capitated payments Medicaid made to a managed-care plan. Conversely, a large letter is not proof the full sum can be collected: the available estate, exempt survivors and hardship law all matter. Readers should treat the alleged 60-day foreclosure threat as uncorroborated, not a nationwide rule.
What Washington requires—and what it leaves up to the states
Congress made Medicaid estate recovery mandatory in the Omnibus Budget Reconciliation Act of 1993. Under CMS guidance and 42 U.S.C. §1396p(b), a state generally must seek repayment from the estate of someone aged 55 or older for Medicaid-funded nursing-facility care, home- and community-based services, and related hospital and prescription drug services. Certain permanently institutionalized people younger than 55 may also be subject to recovery.
There is no nationwide rule that every ordinary doctor visit after age 55 is recoverable. States may choose broader recovery for other Medicaid-covered services; some do. Medicare is a different program, and ordinary Medicare benefits are not automatically collectible through Medicaid estate recovery. Medicaid payments for certain Medicare cost-sharing assistance are specifically excluded.
All states must respect the federal protections for a surviving spouse, a child under 21, or a child who is blind or disabled. Recovery from the deceased Medicaid recipient’s estate cannot proceed while those statutory protections apply. But in some states a deferred claim may later attach to property passing through the surviving spouse’s estate, subject to state rules. That is not the same as making every surviving spouse personally liable.
States must also offer a procedure for waiving recovery that would cause undue hardship. What qualifies, which documents heirs must supply, and how quickly they must act depend on the jurisdiction. States may assert certain lifetime liens on the homes of permanently institutionalized recipients, but federal law sharply limits when and against whose homes that can happen. That is separate from a post-death estate claim.
The hidden second bill: insurance premiums for care never used
The 2024 KFF survey, which received responses from 49 states and Washington, D.C. but not Florida, found that 32 states reported pursuing all Medicaid benefits for at least some enrollees 55 and older, while five reported some additional optional benefits. Thirty states reported recovering managed-care premiums. These numbers describe a 2024 survey, not a freshly audited 2026 count.
In managed care, a state can pay a private plan a monthly capitation even if a beneficiary receives little care that month. Under federal rules, recoverability depends on the plan, the services for which the person is legally subject to recovery, and the state’s chosen scope. This is why a relative cannot simply multiply four months in a facility by an assumed daily price to decide whether a Medicaid claim is legitimate.
The 50-state comparison: which property can be reached?
The first question is which services can be billed. The second is which property counts as the estate. Federal law sets the probate estate as a floor but permits broader definitions reaching certain transfers outside probate, including life estates, jointly held interests, trusts or other arrangements. Deed law, creditor rights and prior liens still matter.
The following snapshot uses a 50-state statutory cross-reference checked September 23, 2026 by an independent law practice; the property-reach column is a general characterization, not a ruling about any particular home. The separate service-scope column identifies the 14 states an August 2026 policy review says had already limited recovery to federal mandatory services as of March 2025. A dash or “not confirmed minimum-only” does not prove every optional benefit is recoverable today. State agency guidance and the law effective on the relevant death date control.
Reading the labels: “Probate only” means the estate-recovery program generally uses probate assets; “beyond probate” signals authority to reach additional interests; “partly beyond” means specific additional interests. Crucially, probate-only does not mean a revocable trust, beneficiary deed or predeath lien is automatically protected. Some nonprobate property remains liable under separate creditor statutes.
| State | General estate reach | Mandatory-services-only baseline? | Principal authority to check |
|---|---|---|---|
| Alabama | Probate only | Not confirmed minimum-only in 2025 survey | Ala. Admin. Code 560-X-33-.05–.06 |
| Alaska | Probate only | Not confirmed minimum-only in 2025 survey | Alaska Stat. §47.07.055 |
| Arizona | Probate only | Not confirmed minimum-only in 2025 survey | Ariz. Rev. Stat. §36-2935 |
| Arkansas | Probate only | Reported federal-minimum scope as of March 2025 | Ark. Code §20-76-436 |
| California | Probate only | Reported federal-minimum scope as of March 2025 | Cal. Welf. & Inst. Code §14009.5 |
| Colorado | Partly beyond probate | Reported federal-minimum scope as of March 2025 | Colo. Rev. Stat. §25.5-4-302 |
| Connecticut | Partly beyond probate | Reported federal-minimum scope as of March 2025 | Conn. Gen. Stat. §17b-95 |
| Delaware | Probate only | Not confirmed minimum-only in 2025 survey | 25 Del. C. §§5001–5006 |
| Florida | Probate only | Not confirmed minimum-only in 2025 survey | Fla. Stat. §409.9101 |
| Georgia | Beyond probate | Not confirmed minimum-only in 2025 survey | Ga. Code §49-4-147.1 |
| Hawaii | Probate only | Not confirmed minimum-only in 2025 survey | Haw. Rev. Stat. §346-37 |
| Idaho | Beyond probate | Not confirmed minimum-only in 2025 survey | Idaho Code §56-218 |
| Illinois | Probate only | Not confirmed minimum-only in 2025 survey | 305 ILCS 5/5-13 |
| Indiana | Beyond probate | Not confirmed minimum-only in 2025 survey | Ind. Code §§12-15-9 et seq. |
| Iowa | Beyond probate | Not confirmed minimum-only in 2025 survey | Iowa Code §249A.53 |
| Kansas | Beyond probate | Not confirmed minimum-only in 2025 survey | Kan. Stat. §39-709(k) |
| Kentucky | Beyond probate | Not confirmed minimum-only in 2025 survey | 907 Ky. Admin. Reg. 1:585 |
| Louisiana | Probate only | Reported federal-minimum scope as of March 2025 | La. Rev. Stat. §46:153.4(D) |
| Maine | Partly beyond probate | Reported federal-minimum scope as of March 2025 | 22 Me. Rev. Stat. §14 |
| Maryland | Probate only | Reported federal-minimum scope as of March 2025 | Md. Health–General §15-121 |
| Massachusetts | Probate only | Reported federal-minimum scope as of March 2025 | Mass. Gen. Laws ch.118E, §31 |
| Michigan | Probate only | Not confirmed minimum-only in 2025 survey | Mich. Comp. Laws §§400.112g–k |
| Minnesota | Beyond probate | Reported federal-minimum scope as of March 2025 | Minn. Stat. §256B.15 |
| Mississippi | Probate only | Reported federal-minimum scope as of March 2025 | Miss. Code §43-13-317 |
| Missouri | Probate only | Not confirmed minimum-only in 2025 survey | Mo. Rev. Stat. §473.398 |
| Montana | Beyond probate | Reported federal-minimum scope as of March 2025 | Mont. Code §53-6-167 |
| Nebraska | Beyond probate | Not confirmed minimum-only in 2025 survey | Neb. Rev. Stat. §68-919 |
| Nevada | Beyond probate | Not confirmed minimum-only in 2025 survey | Nev. Rev. Stat. §422.29302 |
| New Hampshire | Beyond probate | Not confirmed minimum-only in 2025 survey | N.H. Rev. Stat. §167:14 |
| New Jersey | Beyond probate | Not confirmed minimum-only in 2025 survey | N.J. Stat. §30:4D-7.2 |
| New Mexico | Probate only | Not confirmed minimum-only in 2025 survey | N.M. Stat. §§27-2A-1 et seq. |
| New York | Probate only | Not confirmed minimum-only in 2025 survey | N.Y. Soc. Serv. Law §369 |
| North Carolina | Probate only | Not confirmed minimum-only in 2025 survey | N.C. Gen. Stat. §108A-70.5 |
| North Dakota | Beyond probate | Not confirmed minimum-only in 2025 survey | N.D. Cent. Code §50-24.1-07 |
| Ohio | Beyond probate | Not confirmed minimum-only in 2025 survey | Ohio Rev. Code §5162.21 |
| Oklahoma | Probate only | Not confirmed minimum-only in 2025 survey | 63 Okla. Stat. §5051.3 |
| Oregon | Beyond probate | Not confirmed minimum-only in 2025 survey | Or. Rev. Stat. §416.350 |
| Pennsylvania | Probate only | Not confirmed minimum-only in 2025 survey | 62 Pa. Stat. §1412 |
| Rhode Island | Probate only | Not confirmed minimum-only in 2025 survey | R.I. Gen. Laws §40-8-15 |
| South Carolina | Probate only | Not confirmed minimum-only in 2025 survey | S.C. Code §43-7-460 |
| South Dakota | Beyond probate | Reported federal-minimum scope as of March 2025 | S.D. Codified Laws §28-6-23 |
| Tennessee | Probate only | Not confirmed minimum-only in 2025 survey | Tenn. Code §71-5-116 |
| Texas | Probate only | Reported federal-minimum scope as of March 2025 | Tex. Gov’t Code §546.0403; 1 TAC ch.373 |
| Utah | Beyond probate | Not confirmed minimum-only in 2025 survey | Utah Code §26B-3-1013 |
| Vermont | Probate only | Reported federal-minimum scope as of March 2025 | 33 V.S.A. §1906a |
| Virginia | Beyond probate | Not confirmed minimum-only in 2025 survey | Va. Code §32.1-326.1 |
| Washington | Beyond probate | Not confirmed minimum-only in 2025 survey | Wash. Rev. Code §41.05A.090 |
| West Virginia | Probate only | Not confirmed minimum-only in 2025 survey | W. Va. Code §9-5-11c |
| Wisconsin | Beyond probate | Not confirmed minimum-only in 2025 survey | Wis. Stat. §49.496 |
| Wyoming | Beyond probate | Not confirmed minimum-only in 2025 survey | Wyo. Stat. §§42-4-206–207 |
District of Columbia, included for completeness but not one of the 50 states: generally probate-only; 29 DCMR §§6700–6799. The survey categories and the underlying laws have exceptions. For house-specific planning, check the state’s current agency policy, property title, death date and governing statutes, not the chart alone.
Four borders, four different outcomes
California: a deliberate retreat from aggressive recovery
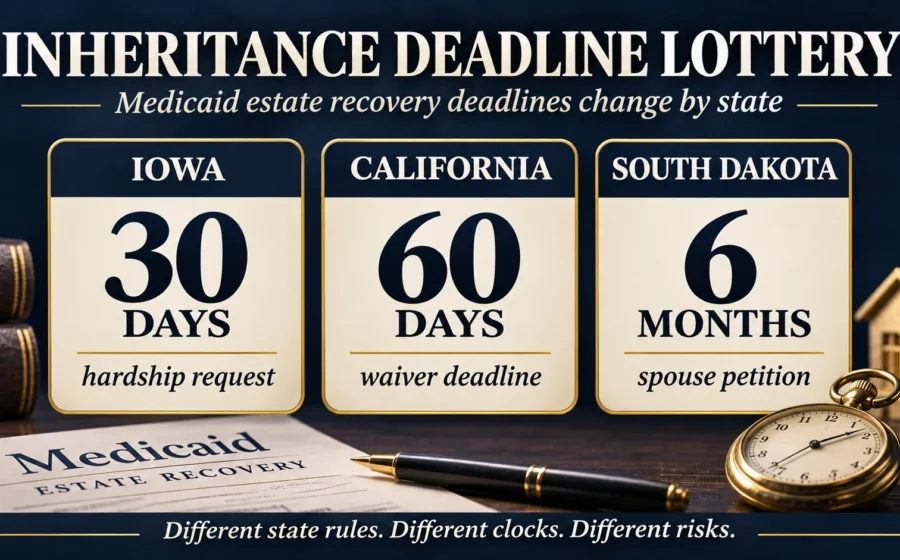
California’s Medi-Cal estate recovery policy changed for deaths on or after January 1, 2017, following SB 833. Recovery generally is limited to probate assets and mandated long-term-care-related services. A family with a qualifying nonprobate transfer may face a different result than a family whose house passes under a will, though transfer rules and creditor claims require an attorney’s review. California’s hardship application deadline is 60 days from the claim letter. That deadline is to seek a waiver; it is not a universal 60-day foreclosure countdown.
Iowa: the insurance-payment surprise
In Perry, Iowa, Fran Ruhl died in January 2022. Her family received a letter seeking $226,611.35 in Medicaid reimbursement, according to a KFF Health News investigation. Her husband, Henry, still occupied a small house valued for tax purposes at $81,470. The family feared the house might eventually be sold, but the six-figure claim was not the amount automatically recoverable from an $81,470 home. Iowa’s program can count payments made to managed-care companies. The case underscores a distinction: the state may claim a very large sum even when it can collect far less.
Another Iowa investigation in February 2025 documented claims exceeding $4.2 million against the estates of people with severe disabilities who had lived in a state institution. The families were stunned; in one case the daughter, Kristin Higgins, was 41 when she died. The letters did not mean that the parents personally owed $4.2 million. The state was seeking property, if any, in the deceased beneficiaries’ estates. Read the documented Iowa cases.
Tennessee: the house can become the subject of court proceedings
In Knoxville, Tennessee, Imani Mfalme faced a TennCare claim of approximately $225,000 against her late mother’s estate. The Associated Press reported that Tennessee sought a legal path to force sale of the house. That is meaningful evidence of enforcement pressure—but it is not evidence that Medicaid automatically auctions a home on day 60. Tennessee’s official estate recovery page explains recovery as a claim against the estate, not a personal invoice imposed on an adult child merely for being related.
Massachusetts: state legislation changed the bill
Massachusetts previously pursued broad Medicaid spending, helping produce stories such as the Associated Press’s account of Sandy LoGrande confronting a $177,000 claim after her father’s death. For people dying on or after August 1, 2024, however, Massachusetts General Laws chapter 118E, §31 narrows age-55-plus recovery to the federally mandated long-term-care categories. MassHealth’s guidance also describes an exemption for probate estates valued at $25,000 or less, along with additional safeguards. The change depends on the date of death; the new rule should not be portrayed as automatically canceling older claims.
Other state contrasts that can decide whether an heir keeps the keys
Georgia: Georgia’s official program generally uses a broad estate definition, while its policies exempt estates within a specified small-estate threshold and provide other exclusions. Title structure, home value and hardship rules interact. A mere change in deed is not a reliable universal workaround.
Minnesota: state guidance and Minn. Stat. §256B.15 allow recovery beyond a simple probate-only model. A transfer-on-death deed may avoid probate but still leave the recipient’s equity subject to statutory recovery or creditor rights.
Texas and Florida: both are generally probate-focused, yet the often-recommended Lady Bird deed, homestead protections and trust rules are not interchangeable. Texas’ 2026 administrative rule changes do not mean the entire estate-recovery mandate was repealed. Florida’s homestead law can be especially important, but neither a YouTube comment nor a generic web form is adequate deed advice.
Illinois: its official recovery program takes a generally probate-based approach, but hardship and repayment arrangements are not interchangeable with those in other states. Washington: KFF reports that certain hardship circumstances may result in deferral rather than permanent waiver. West Virginia: the 2024 KFF survey identified a modest-value-home threshold of $50,000, versus less than $10,000 in Texas and less than $5,000 in Mississippi and North Dakota. These are survey-era program criteria, not free-standing national homestead exemptions.
The other law being confused with Medicaid recovery: when can a child be sued?
Online warnings often merge two legal systems. Medicaid estate recovery is generally a claim against the deceased recipient’s estate. Filial-responsibility laws, which survive in a number of states, can sometimes create personal liability for an adult child’s parent’s unpaid support or care—but their wording, applicability and enforcement vary dramatically.
The most recognizable example is Health Care & Retirement Corp. of America v. Pittas (Pa. Super. Ct. 2012), where a nursing facility won a judgment of $92,943.41 against a son under Pennsylvania’s filial-support statute. The mother had left a private nursing-care bill unpaid. That case was not a Medicaid estate-recovery lien on a paid-off house. Nor is there a newly enacted federal law making all adult children liable for their parents’ Medicaid care in January 2027. Cases and statutes in this separate category require their own careful analysis.
Five strategies people misunderstand—and the defenses worth checking
- “The house is exempt while Mom lives, so it is safe when she dies.” Not necessarily. Medicaid’s eligibility disregard for certain homes and its later estate-recovery rules are separate.
- “A will protects the house.” A will commonly sends property through probate. That may expose it to valid creditor and estate-recovery claims.
- “A revocable living trust solves it.” Not universally. States and general trust-creditor laws differ. Some states can reach certain trust assets even where estate recovery is described as probate-only.
- “Give the house to the children right before nursing care.” Medicaid long-term-care eligibility generally examines transfers within a 60-month lookback, with penalizing rules and narrow exceptions. An improvised gift can affect care eligibility, taxes, control over the home and other family claims.
- “An irrevocable trust always shields it after five years.” No. Validity depends on timing, retained powers, trust language, state creditor law, beneficiary rights and what is funded. “Five years” is not a blanket blessing.
Federal law does contain specific exemptions or exceptions for transfers involving a spouse, certain minor or disabled children, a qualifying co-owning sibling who lived in the home, or a caregiving child whose residence and care delayed institutionalization. A caregiver-child exception commonly requires at least two years of residence and evidence of the qualifying care. Long-term-care partnership insurance can provide a separate form of asset protection in participating states. These are document-intensive rules; families should not deed away property on the strength of a video.
A claim letter arrives: the practical response
Preserve the envelope and note the date. Ask the agency for an itemized claim with service dates, Medicaid eligibility category, managed-care premiums, any offsets and the asserted legal authority. Confirm whether the notice is an informational claim, a probate filing, or a recorded lien; check public land and court records if appropriate. Identify qualifying surviving spouses, children, transfers, exemptions, hardship standards and deadlines. If a deadline is imminent, seek an elder-law or probate lawyer in the relevant state before transferring or selling anything. Many local legal-aid and Area Agency on Aging offices can help families locate assistance.
A demand greater than the home’s value is not a $100,000 personal debt for an adult child simply because of kinship. A surviving spouse’s deferral does not necessarily extinguish every later claim, either. And no homeowner should confuse Medicaid, Medicare, an ordinary mortgage, a reverse mortgage, a provider’s unpaid private bill, and a state’s probate claim. They are legally different instruments.
Washington is changing Medicaid. Is estate recovery next?
A 2025 federal reconciliation law, P.L. 119-21, changed other aspects of Medicaid. Its January 1, 2028 provision generally caps certain home-equity limits for Medicaid long-term-care eligibility at $1 million, with special provisions for farms. That is not a new $1 million estate lien or an automatic expansion of what states may recover after death. The law also narrows retroactive Medicaid eligibility from three months to two for many traditional Medicaid groups and one month for some expansion adults, effective January 1, 2027. See the Congressional Research Service analysis and KFF comparison.
Separately, the Stop Unfair Medicaid Recoveries Act, H.R. 6951, was introduced in January 2026 to challenge federal estate-recovery requirements. Introduction is not enactment; the existing federal duty remains in force. Claims that budget pressure will necessarily cause more aggressive recoveries are predictions, not yet measured outcomes.
The real national imbalance: tiny budget relief, enormous household stakes
States recovered approximately $733 million nationally in fiscal year 2019, according to the Medicaid and CHIP Payment and Access Commission. That amounted to roughly one-tenth of 1 percent of total Medicaid spending. KFF found extreme variation in recovery intensity and the rules for hardship relief. A dollar figure that is modest in a federal program can still represent the entire accumulated wealth of a family whose principal asset is a modest house.
There is a principled case for asking estates with assets to reimburse taxpayers who funded expensive care. There is also a serious equity objection: well-advised families may have more lawful planning options, while households with little more than an owner-occupied home confront complicated law and short response deadlines after a funeral. Both questions deserve evidence, not panic.
The unanswered question is not whether the government has authority to pursue a paid-off home. It does, subject to law. The deeper question is why two families with similar homes and identical care needs may have different inheritance outcomes solely because they live on opposite sides of a state border—and whether legislators believe that difference is defensible.
Source documents and further reading
- CMS: Federal estate-recovery guidance; 42 U.S.C. §1396p: Federal statutory language.
- KFF, 2024 survey of state recovery policies and hardship exceptions.
- State statutes and property-reach analysis, September 2026; 2026 policy review of state minimum-scope laws.
- KFF Health News: Iowa Ruhl case; KFF Health News: multimillion-dollar Iowa claims; AP: Tennessee and Massachusetts family cases.
- California Medi-Cal; MassHealth; Minnesota DHS; Georgia Medicaid; TennCare.
- H.R. 6951 (2026), bill status; 2025 federal reconciliation-law provisions.
Video: the viral warning that started this investigation
Watch “Medicaid Issues WARNING to Every Homeowner With a Paid-Off Home” on YouTube. Source commentary, not a verified record of the alleged $190,000 house, $114,000 lien or foreclosure deadline. This investigation independently checks its legal claims and documents its limitations.
Editorial/legal note: This article compares general statutes and published guidance as of November 10, 2026. It is not individualized legal advice. Administrative rules, court decisions, eligibility categories, property title, death dates and hardship facts can change the result.
Follow-up: Find your state and your filing deadline
Apep Bar has since published a searchable 50-state estate-recovery reference with statute pointers, official contacts and hardship rules, plus a separate exposé on the deadlines and waiver differences that can determine whether heirs receive relief. Updated Texas guidance: Texas HHS’s November 2026 public page now lists a $15,000-or-less estate threshold and a $5,000-or-less Medicaid cost threshold; the lower Texas figures in the 2024 KFF survey quoted earlier above are historical, not the current agency rules. See Texas HHS’s official MERP guidance.