
Apep Bar Investigation | November 4, 2026. A Connecticut couple fought a vehicle-tax assessment after a private contractor photographed their car in a city where they said it did not live. The appeal succeeded. The machinery that generated the bill remains.
Eight photographs. Two parking tickets. A college student’s commute. And an unexpected demand for vehicle property taxes from a city that wasn’t home.
That is the dispute Paul and Kathy Garasimowicz described to NBC Connecticut in an October 29 investigation. The couple said they lived in North Branford, paid their car taxes there and allowed their son to use their Nissan while attending college, working and visiting his girlfriend in New Haven.
Yet New Haven’s tax-enforcement contractor, Municipal Tax Services (MTS), had recorded the car in the city multiple times. The family received a notice asserting that the vehicle could be taxable there. Months later, New Haven’s Board of Assessment Appeals dropped the assessment.
The viral version calls this the beginning of America’s surveillance state. The documented version poses a more precise question: What happens when a private company can turn location sightings into tax investigations—and gets paid when those investigations produce revenue?
Watch the Coverage
Original reporting: Watch/read NBC Connecticut Responds’ investigation, including the station’s interviews and reporting on the disputed tax assessment.
Viral video commentary: View the X video that brought this story to wider attention. This is commentary circulating online, not evidence that each claim in its caption is verified. In particular, its $9 million-in-one-year claim is not established by the records described below.
Additional viewer-supplied clip: Watch the related TikTok video (external platform; its contents could not be independently authenticated). For the underlying facts, rely on the linked NBC reporting and cited records.
How a College Commute Turned Into a Tax Case
According to NBC Connecticut’s reporting, MTS supplied the Garasimowiczes with eight images of their Nissan taken in New Haven and two parking tickets. The couple said their son traveled there often for school, work and his personal life but lived at the family’s North Branford home.
They submitted school and work documentation, mortgage statements and proof of taxes already paid in North Branford. Kathy said MTS nevertheless told them their evidence was insufficient. She said a subsequent telephone conversation left her feeling pressured to pay; MTS denied pressuring the family. The company provided NBC with a written call transcript, not an audio recording, leaving the completeness of that account uncertain.
The contractor also told NBC it had found credit-related address information connecting the son to New Haven, without identifying exactly what that information was. The family said he had no New Haven lease or utilities in his name and was reluctant to send still more sensitive documents to a private firm.
The couple said the city’s assessor’s office directed them back to MTS. In September 2026, they took their dispute to New Haven’s Board of Assessment Appeals. NBC reported that after a board member asked whether the son had ever lived in New Haven, the board dropped the assessment.
That distinction matters: the outcome was an overturned municipal assessment after an appeal, not proof that every MTS investigation is invalid or that the company itself has legal authority to impose taxes.
What the Cameras Actually Do
On its own technology page, Municipal Tax Services describes portable automatic license-plate-recognition equipment that captures plate characters, vehicle images and GPS-linked times and locations. The equipment can ride in a vehicle as field investigators patrol local streets.
Put simply, it can establish that a plate was observed at a certain place and time. It does not, by itself, tell an assessor where that vehicle is normally garaged overnight or why a driver visited a particular neighborhood.
MTS says on its services page that its role is to investigate unregistered or improperly registered vehicles and support municipal assessors; the company states that it does not assess or collect taxes itself. The assessment remains a government function. But the contractor’s evidence and initial interactions with motorists can shape which cases reach that government process.
This case concerns MTS’s mobile plate-scanning operation, not necessarily Flock Safety’s separate network of fixed license-plate cameras. The technologies share privacy questions, but they should not be conflated. For Apep Bar’s wider examination of automatic plate surveillance, see Standing Up to Flock: How Communities Are Challenging America’s License-Plate Surveillance Network.
The Legal Test: Where a Car Lives, Not Everywhere It Visits
Under Connecticut General Statutes Section 12-71, a motor vehicle generally belongs on the tax list of the municipality from which it most frequently leaves and to which it returns, or where it normally remains. The statute also sets a presumption tied to the owner’s residence, subject to statutory qualifications and evidence.
That is different from a rule taxing every car that parks in a city. A student commuting to class, someone visiting family or a person working across town can generate numerous camera observations without necessarily moving the car’s primary taxing location.
New Haven has a legitimate enforcement interest in identifying vehicles actually kept in the city but registered elsewhere. Officials argue that residents who improperly register vehicles shift costs onto neighbors who follow the rules. The question raised by this case is not whether towns may investigate tax evasion. It is how confidently sightings and third-party address information should be treated, and how readily a resident can correct a mistake.
The 38% Commission, the $50 Fee—and a Misleading $9 Million Claim
Here is where the financial incentive becomes central. NBC Connecticut obtained the city’s agreement with MTS through a public-records request and reported that the contractor receives 38% of recovered vehicle-tax revenue. The agreement also provides for a $50 per-vehicle fee charged to the vehicle owner. Earlier local reporting quoted New Haven’s assessor describing the same 38% rate as a share of taxes actually collected.
The widely shared claim that MTS received $9 million in commission in a single year should not be stated as established fact. NBC quoted a New Haven figure of nearly $24 million recovered between 2024 and 2025, then observed that 38% of that amount would be roughly $9.1 million. The story does not publish payment records establishing that MTS was actually paid that sum, much less in one year.
There is an additional accounting problem. In the same NBC report, Mayor Justin Elicker said roughly 1,350 vehicles identified in 2025 generated an additional $10 million in tax assessment value. Assessment value is not tax revenue. At New Haven’s published motor-vehicle rate of 32.46 mills, $10 million in assessed vehicle value corresponds to approximately $324,600 in one year’s tax levy before adjustments—not $10 million collected.
Without the underlying accounting records, it is unclear how the reported $24 million figure was defined, what portion constituted taxable assessments or actual collections, and how much commission MTS ultimately received. None of that erases the contractual incentive. It simply means the viral payout number is not sufficiently verified.
A percentage-of-recovery contract can reward successful enforcement. It can also raise an obvious conflict-of-incentives concern when the same private contractor identifies suspected cases and handles a resident’s first attempt to dispute them. The open question is whether the city imposes adequate independent review before someone is billed, rather than only after a dispute escalates.
New Haven Defends the Program—and the Appeals Process
Mayor Elicker defended the arrangement in a statement reported by NBC, saying most residents meet their tax obligations and that the city needs to make sure others pay what they owe. He reported that MTS had established more than 3,000 cases since the program began in 2022, with only two reaching the Board of Assessment Appeals. The city said an address history gave investigators reason to suspect the Garasimowicz family’s son lived in New Haven and acknowledged that mistakes can occur.
Those statistics show the scale of the program; they do not establish that every unappealed assessment was accurate. Some recipients may agree they owe the tax. Others may successfully resolve cases earlier or may never pursue a formal board hearing. The cited figures do not distinguish those outcomes.
New Haven’s own tax information directs people who receive a bill for a car not garaged in the city to contact the assessor. Its Board of Assessment Appeals explains the city’s formal appeals process. These public channels matter, especially if a contractor’s response leaves a vehicle owner unable to resolve the underlying factual dispute.
Six Municipalities, Years of Potential Data Retention
MTS told NBC it had contracts in New Haven, Enfield, New London, Norwich, Ansonia and Norwalk. The company said it shares plate data with its municipal clients, does not sell the information and can retain information for up to 15 years.
That is a consequential point even apart from any tax bill. Repeated observations can create a detailed location history: where a vehicle was photographed, at what time, and how often. Even when the initial purpose is mundane tax compliance, a privately held archive of movement records prompts questions about retention policies, access logs, accuracy, correction rights and what happens to data from people who owe nothing.
This program is not brand new. A Connecticut legislative research report from 2014 already described MTS employees using camera technology to identify potentially misregistered vehicles. What makes the Garasimowicz dispute newly revealing is how the technology, financial arrangement and burden of challenging a disputed inference came together for one family.
What a Fairer Process Would Have to Answer
The couple’s case ended in their favor, but it leaves questions worth asking of every municipality using this approach. Are location sightings treated as leads or presumptive proof? Who sees the evidence before a bill is issued? Can motorists challenge inaccurate credit-address records without surrendering additional personal information to a contractor? What records establish contractor payments, and how long are innocent motorists’ plate scans stored?
Authorities can pursue actual unpaid taxes without pretending a camera knows where a person lives. A plate reader records a sighting. Turning that sighting into a debt requires more than software, a commission schedule and an envelope.
The family’s bill was dropped. The bigger question remains: who audits the surveillance system before it sends the next one?
Sources, Records and Original Reporting
- NBC Connecticut Responds, October 29-30, 2026: original interviews with the family, city and MTS; contract and appeals reporting. View the broadcaster’s coverage at the source.
- Municipal Tax Services: description of its automated plate-recognition technology.
- Municipal Tax Services: description of investigative services and claimed distinction from tax assessment and collection.
- Connecticut General Statutes, Chapter 203, Section 12-71: vehicle taxing jurisdiction.
- New Haven Register, July 28, 2025: prior figures separating assessed vehicle value from tax bills and explaining the contractor’s percentage.
- City of New Haven: Board of Assessment Appeals and procedures.
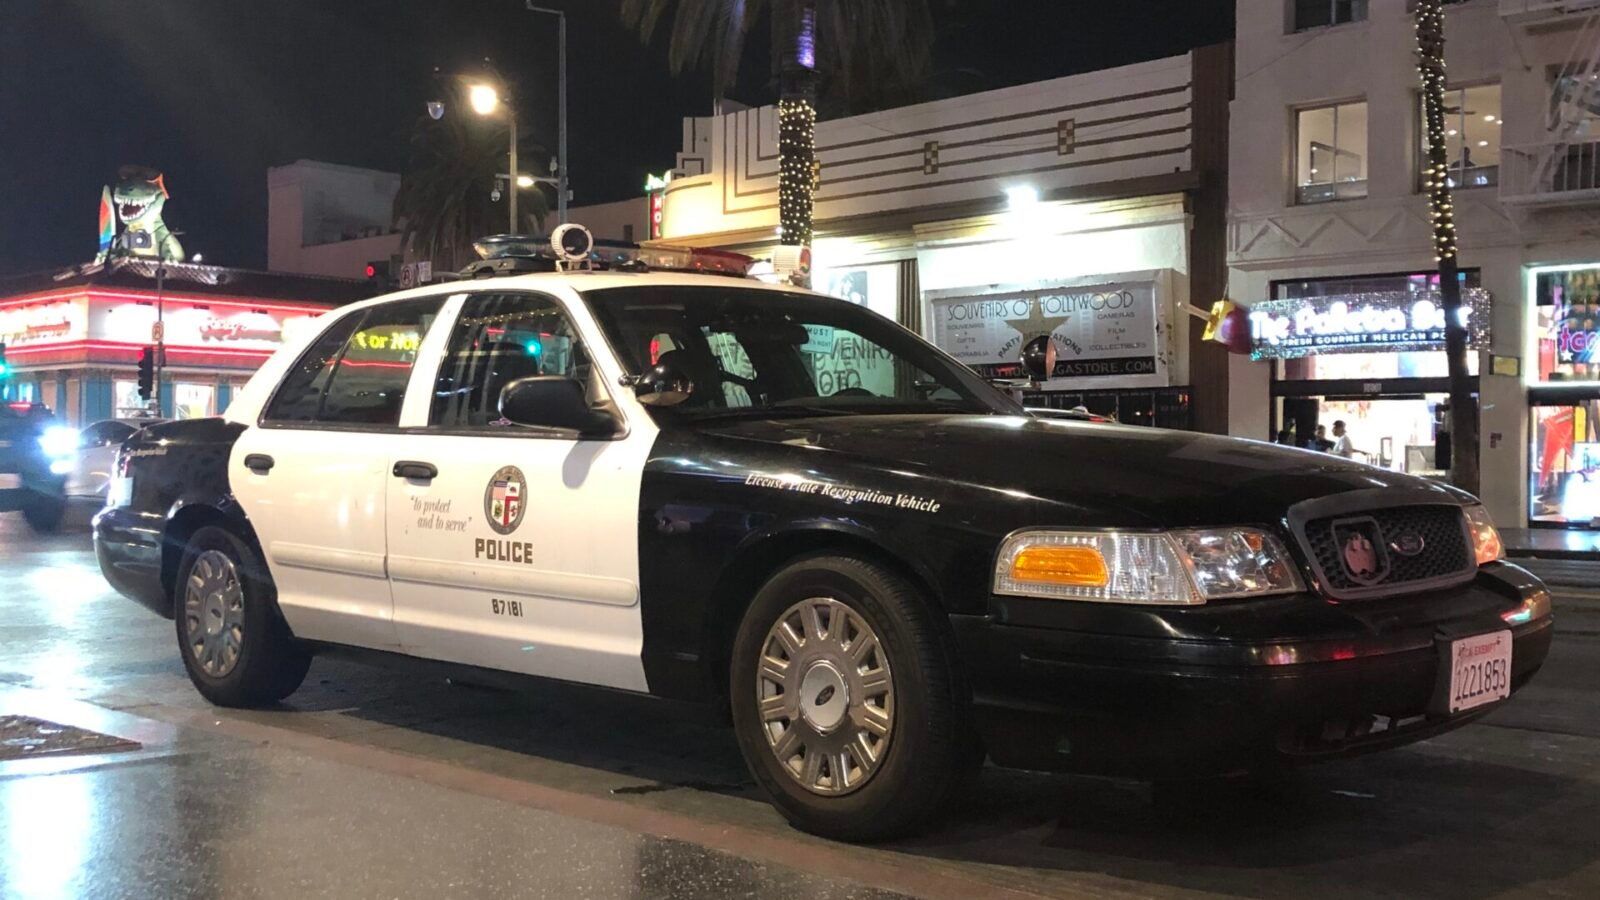
Visual disclosure: Featured photograph: a real license-plate-reader-equipped police car, photographed in 2022 by LouieRBLX / Wikimedia Commons (CC BY-SA 4.0). This is contextual technology, not an MTS vehicle, the family, or their Nissan. Apep Bar did not independently interview the parties; case details are attributed to NBC Connecticut’s reporting. The social-media clips circulating this story are not the primary evidence for the facts above.